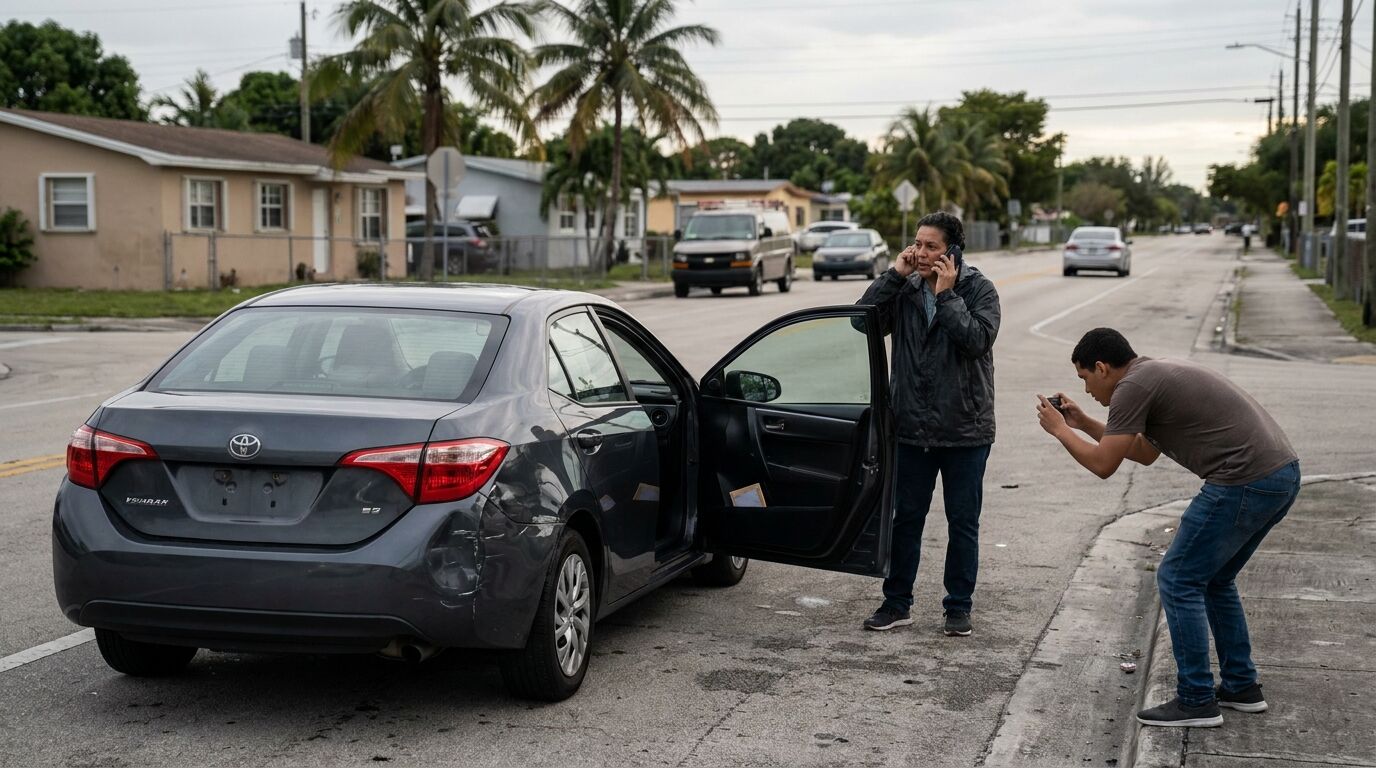
Roughly one in five Florida drivers is on the road with no insurance at all, among the worst uninsured rates in the country, and insurance industry studies have consistently ranked Miami-Dade as the epicenter of the problem. Add the drivers carrying only Florida's bare minimum coverage, which does not even require bodily injury liability, and the practical reality is stark: When you are seriously hurt in a Miami crash, the odds are high that the at-fault driver has little or nothing to pay you with.
The answer Florida law provides is uninsured motorist coverage, UM for short, an optional piece of your own auto policy that steps in and pays what the at-fault driver cannot. In our practice, UM coverage decides more serious injury outcomes than almost any other single factor. It is also the part of the policy drivers most often decline to save a few dollars, usually without understanding what they signed away.
This article explains how UM claims actually work, the difference between uninsured and underinsured cases, the stacking rules that multiply coverage, and why a claim against your own insurer is a real negotiation, not a formality. If you were hit by an uninsured or underinsured driver anywhere in South Florida, the Miami car accident lawyers at Mausner Group Injury Lawyers offer free consultations at 305-344-4878.
Why Miami Is Ground Zero for Uninsured Drivers
Florida's uninsured problem is structural. The state requires only PIP and property damage liability to register a car; bodily injury liability coverage, the insurance that pays the people you hurt, is not mandatory for most drivers. So even many "insured" Florida drivers are uninsured in the way that matters to an injury victim. Layer on the drivers with no policy at all, suspended registrations, and lapsed coverage, and South Florida's roads carry an enormous population of vehicles that cannot pay for the harm they cause.
That reality reshapes injury claims. As we explained in our Florida PIP guide, your own no-fault coverage pays the first $10,000 of medical bills regardless of fault, but $10,000 does not survive first contact with a surgery. Beyond PIP, a serious claim needs a liability policy to pursue, and in Miami-Dade, far too often, there is none.
What UM Coverage Actually Does
Uninsured motorist coverage, governed by Section 627.727, Florida Statutes, turns your own insurer into the substitute for the missing at-fault driver. It pays what that driver's bodily injury coverage would have paid: medical expenses beyond PIP, lost wages, and pain and suffering, up to your UM limits.
UM applies in more situations than most people realize:
- The classic uninsured case, where the at-fault driver carries no bodily injury coverage
- The underinsured case, where the driver has some coverage, but your damages exceed it, and UM pays the gap above their limits
- Hit and run crashes, where the driver is never identified, a constant Miami scenario we see from nightlife districts to residential streets
- You as a pedestrian or cyclist, struck by an uninsured driver while not even in your car
- Passengers, who may claim under the host vehicle's UM policy and sometimes their own household coverage
Florida law takes UM seriously enough that insurers must offer it whenever a policy includes bodily injury coverage, and a rejection is only valid if made in writing on an approved form. A UM rejection an insurer cannot properly document can be challenged, which has salvaged more than one catastrophic case.
Stacking: The Multiplier Most Drivers Do Not Know They Chose
Florida allows stacked UM coverage, which multiplies your limits by the number of vehicles on your policy. Two cars with $100,000 in stacked UM means $200,000 available for your claim. Unstacked coverage, sold at a discount, caps you at the single limit no matter how many cars you insure.
The election is made on a form most people signed years ago and cannot remember. After a serious crash, finding out whether your UM is stacked, and whether the stacking election was validly executed, is one of the first things we check, because the answer can double or triple the money available. Households with multiple policies add another layer, since resident relatives' coverage can sometimes be reached, as well. None of this is volunteered by the insurer. It is found.
A UM Claim Is an Adversarial Claim
Here is the part that surprises people: Once you file a UM claim, your own insurance company steps into the shoes of the uninsured driver and defends against you exactly as the other side's insurer would have. The adjuster evaluating your UM claim is not your advocate. They will dispute the crash facts, question your treatment, send you to their chosen doctors, and argue your comparative fault under the 51 percent bar we covered in our comparative negligence guide.
Everything in our guide to dealing with insurance adjusters applies to UM claims with one addition: Your policy imposes cooperation duties on you, including deadlines, notice requirements, and sometimes an examination under oath. Missing a policy condition can forfeit coverage you paid years of premiums for, which is one more reason UM claims benefit from counsel early.
The flip side is leverage. Florida's bad faith law applies with particular force to UM insurers, and a carrier that lowballs a documented claim within its limits risks exposure beyond those limits. Insurers price represented UM claims accordingly.
The Hit and Run Wrinkle
Miami's hit and run numbers are notorious, and for injury victims the legal path runs straight through UM: A phantom driver is an uninsured driver. Two practical points decide these cases. First, report the crash to police immediately, because prompt reporting both aids any investigation and satisfies policy conditions for phantom vehicle claims. Second, evidence of the unidentified vehicle matters, from paint transfer and damage patterns to witness accounts and nearby camera footage, since insurers sometimes dispute that another vehicle was involved at all. We covered how these issues play out for riders in our e-bike and motorcycle articles, where hit and run UM claims are even more common.
What to Do, Before and After
Before any crash: Buy UM, buy as much as you can afford, and buy it stacked. It is routinely the best-value coverage on a Florida policy, and it is the only one that protects your family from the one in five drivers carrying nothing.
After a crash with an uninsured or underinsured driver: Get medical care within the 14-day PIP window, report the crash, notify your insurer of a potential UM claim without giving a recorded statement about fault or injuries until you have advice, and gather the policy documents, including the UM selection forms. Then, have the claim valued properly before negotiating with a carrier that knows the two-year filing deadline from our statute of limitations guide better than you do. Our Miami car accident practice page explains how we handle UM cases from notice through trial.
Frequently Asked Questions About Uninsured Motorist Claims
What happens if I am hit by an uninsured driver in Florida?
Your own PIP coverage pays the first layer of medical bills, and beyond that, your uninsured motorist coverage, if you carry it, pays what the at-fault driver cannot: remaining medical costs, lost wages, and pain and suffering up to your UM limits. Without UM, recovery often depends on whether the at-fault driver has assets, which is rare.
Is uninsured motorist coverage required in Florida?
No, but insurers must offer it with any policy that includes bodily injury liability, and you can only reject it in writing on an approved form. An improperly documented rejection can be challenged after a crash, sometimes restoring coverage the insurer claims was declined.
What is the difference between uninsured and underinsured motorist claims?
An uninsured claim involves a driver with no bodily injury coverage; an underinsured claim involves a driver whose limits are too small for your damages, with UM paying the amount above their coverage. In Florida both are handled under the same UM provisions of your policy.
What is stacked UM coverage?
Stacking multiplies your UM limits by the number of vehicles on the policy, so $100,000 in stacked UM with two cars provides $200,000. Unstacked coverage holds you to the single limit. The election was made on a signed form, and verifying it after a serious crash is essential because the difference is often the whole case.
Does UM coverage apply to hit and run accidents?
Yes. An unidentified driver is treated as uninsured, which makes UM the recovery path in Miami's frequent hit and run crashes. Report the crash to police promptly and preserve any evidence of the other vehicle, since insurers scrutinize phantom vehicle claims closely.
Will my own insurance company fight my UM claim?
Expect it to. In a UM claim, your insurer stands in the at-fault driver's shoes and defends accordingly, disputing fault, damages, and treatment. The claim is a real negotiation with deadlines and policy conditions, and Florida's bad faith law is the counterweight that keeps carriers honest.
Hit by a Driver With No Insurance? You May Still Have a Strong Case
The coverage that saves these cases is usually sitting in your own policy, and the fight is making your insurer honor it. Mausner Group Injury Lawyers handles UM claims across Miami-Dade and South Florida.
Call 305-344-4878 for a free consultation, available 24/7. You pay nothing unless we win.
This article is for general informational purposes only and does not constitute legal advice. Florida law referenced includes Fla. Stat. 627.727, 627.736, 624.155, 768.81, and 95.11; uninsured driver statistics from Insurance Information Institute and Insurance Research Council studies. Laws change; consult a licensed Florida attorney for advice specific to your situation.
